MEDICARE ADVANTAGE IN UTAH
Medicare Advantage Plans Utah Guide: How Part C Works and 7 Checks Before You Enroll
Medicare Advantage plans in Utah are Medicare-approved private plans that replace how you get Part A and Part B. Most include drug coverage, use a provider network, and have a yearly out-of-pocket limit. You still pay your Part B premium ($202.90 a month for most people in 2026). Which plans you can join depends on your county.
Sources: Medicare.gov – Compare Original Medicare and Medicare Advantage · Medicare.gov – Medicare costs
This guide to Medicare Advantage plans Utah residents can join explains, in plain words, how Part C works, what it costs, how networks and prior authorization work, when you can enroll, and seven checks to make before you pick a plan. It’s education, not a sales pitch. I’m Fores Boo, a licensed independent Medicare agent in Draper. I’ve been licensed since 2014 and have helped 1,000+ Utahns with Medicare.
New to Medicare? Start with the Medicare Utah guide or turning 65 in Utah: your Medicare roadmap.
Want a second set of eyes on your options?
There’s no cost to you for my help.
WHAT IT IS
What Medicare Advantage plans in Utah are
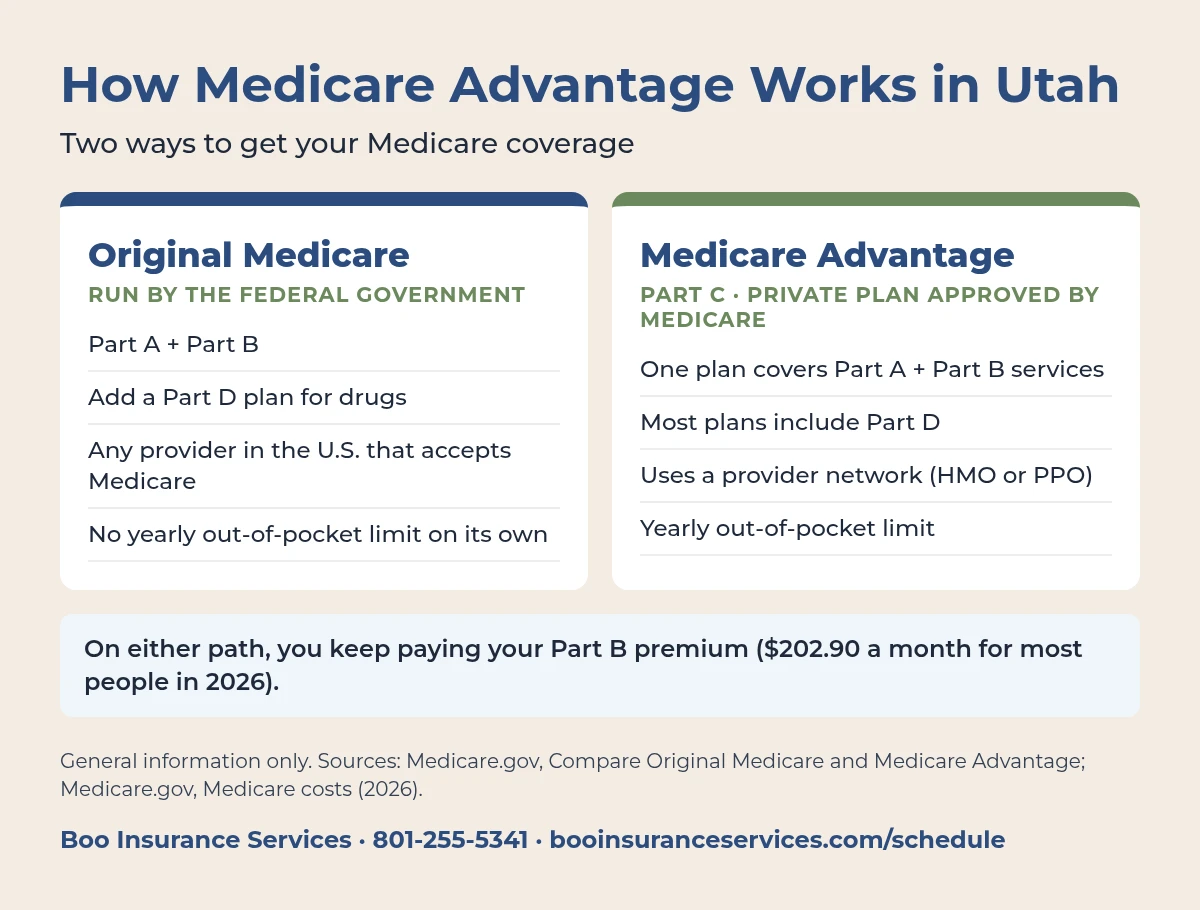
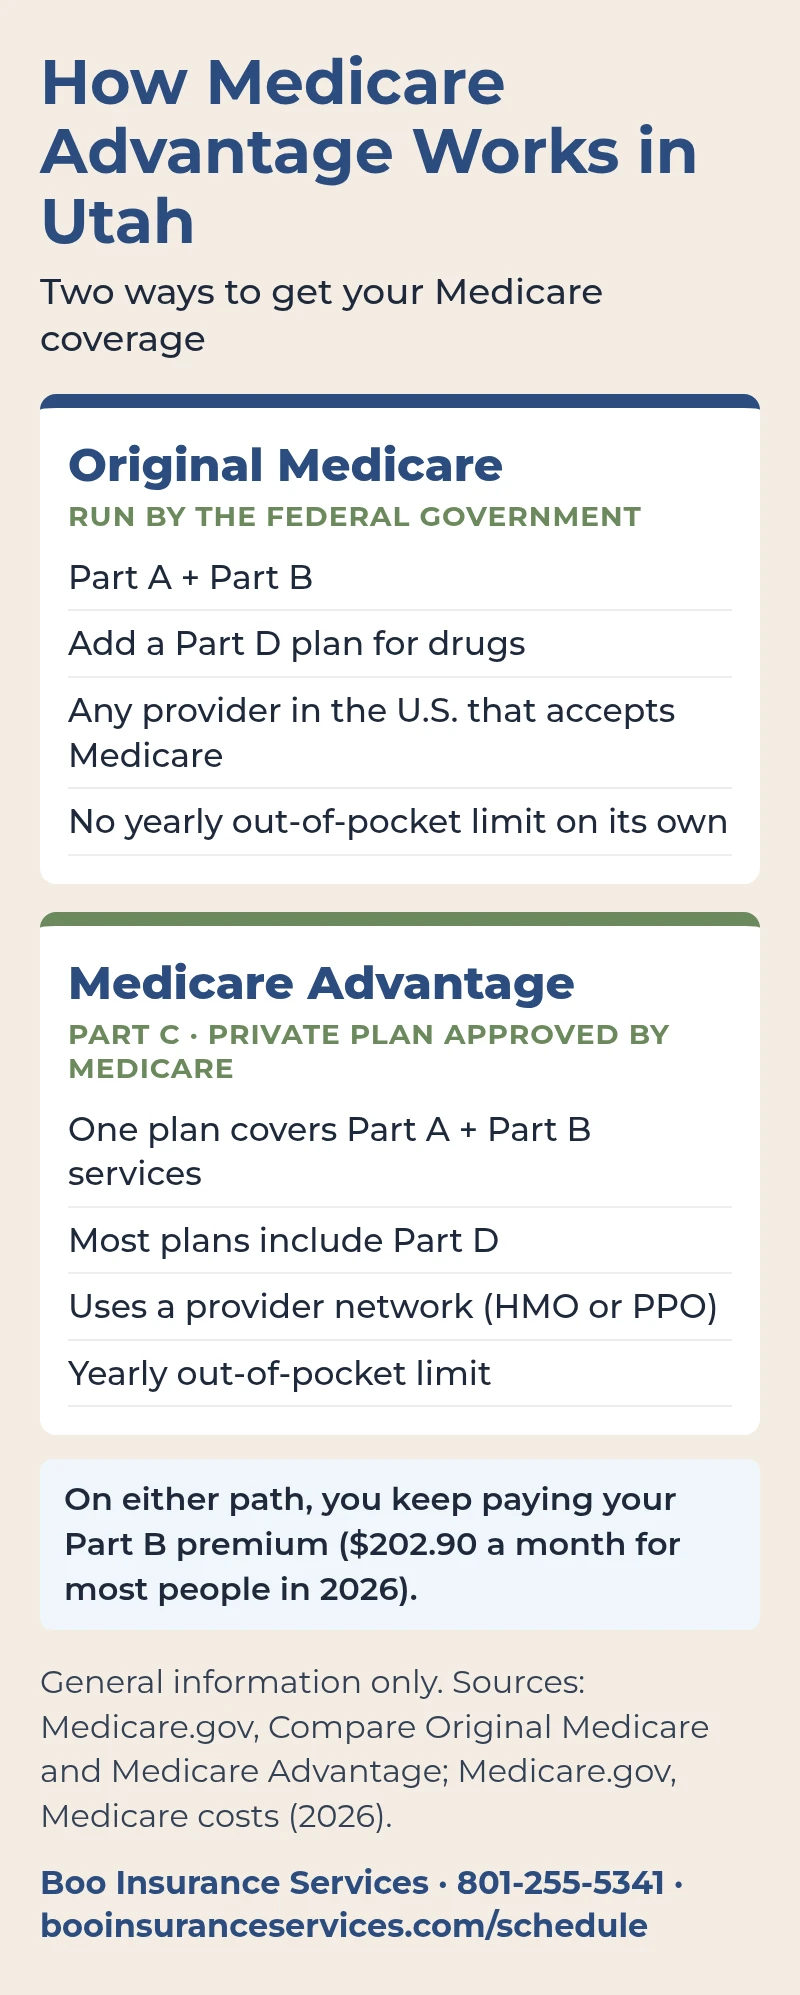
A Medicare Advantage plan, also called Medicare Part C, is a health plan offered by a private company that contracts with Medicare. When you join one, the plan covers your Part A (hospital) and Part B (medical) services instead of Original Medicare paying your doctors directly. (Medicare.gov – Compare Original Medicare and Medicare Advantage)
You’re still in Medicare. You keep your Medicare rights and protections, and you keep paying your Part B premium. Every Medicare Advantage plan must cover the medically necessary services Original Medicare covers. Plans can set different costs and rules, and many add benefits Original Medicare doesn’t cover.
Medicare Advantage is popular in Utah
According to CMS, about 55% of Utahns with Medicare (269,226 of 490,235 people) were in Medicare Advantage or other Medicare health plans in June 2026. The rest were in Original Medicare. (CMS Medicare Monthly Enrollment)
Popular doesn’t mean right for everyone. It means it’s worth understanding how these plans work before the Open Enrollment mailers arrive.
WHAT IT COVERS
What Medicare Advantage plans Utah residents can join usually cover
The core: Part A and Part B services
- Hospital stays, skilled nursing facility care, hospice and some home health care (Part A services).
- Doctor visits, outpatient care, lab tests, preventive services and medical equipment (Part B services).
- Emergency and urgent care anywhere in the U.S., even outside the plan’s network.
Drug coverage (Part D) in most plans
Most Medicare Advantage plans include Part D drug coverage. These are often called MA-PD plans. If you join a plan with drug coverage, you generally can’t also have a separate Part D plan. In 2026, Medicare caps what you pay out of pocket for covered Part D drugs at $2,100 a year. (Medicare.gov – How much does Medicare drug coverage cost?)
Extra benefits vary by plan and county
Many plans add benefits Original Medicare doesn’t cover, such as some dental, vision and hearing care or fitness programs. These extras differ a lot from plan to plan and from one Utah county to the next. Read the plan’s Evidence of Coverage to see the limits, not just the headline.
COSTS
How Medicare Advantage costs work
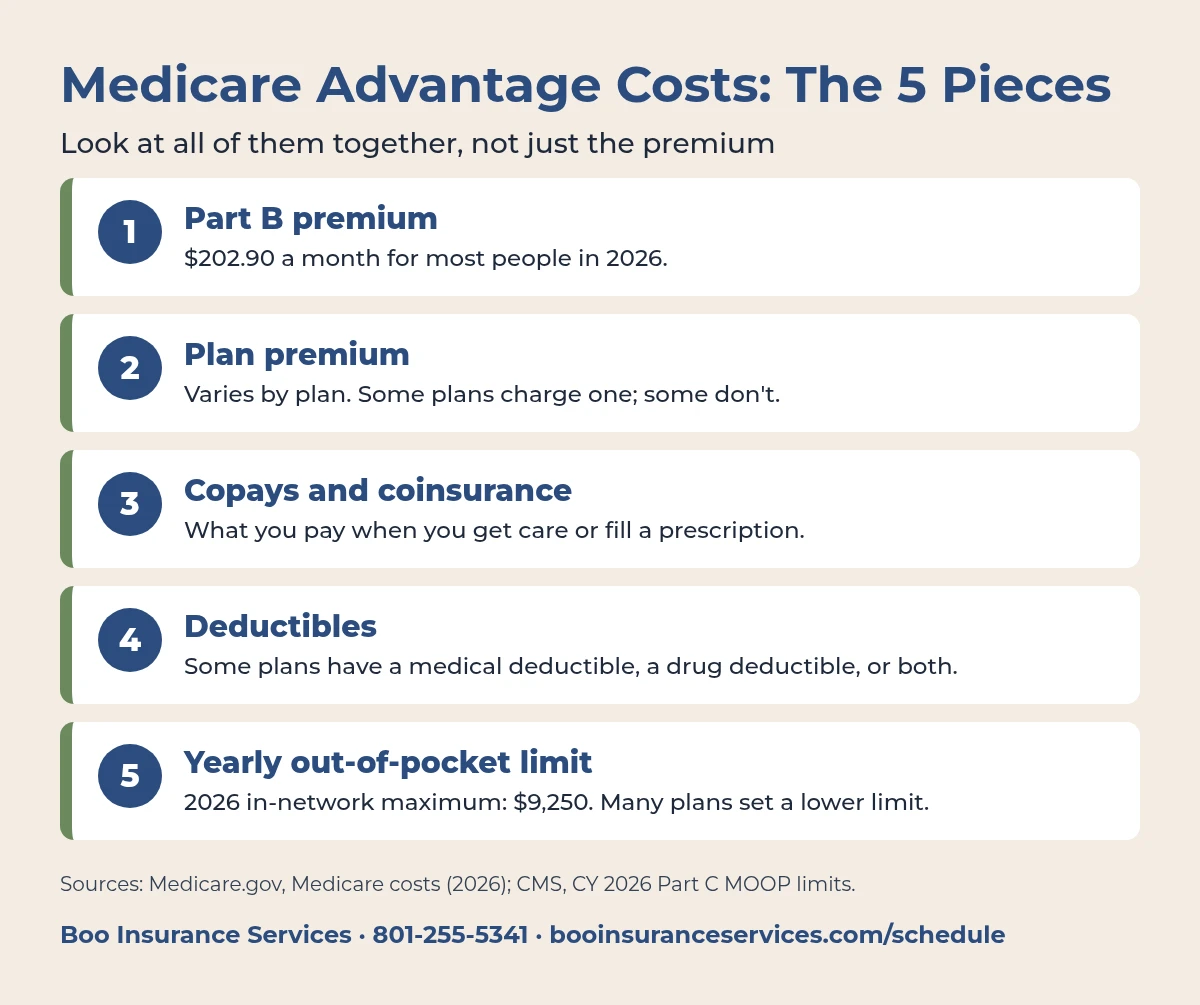
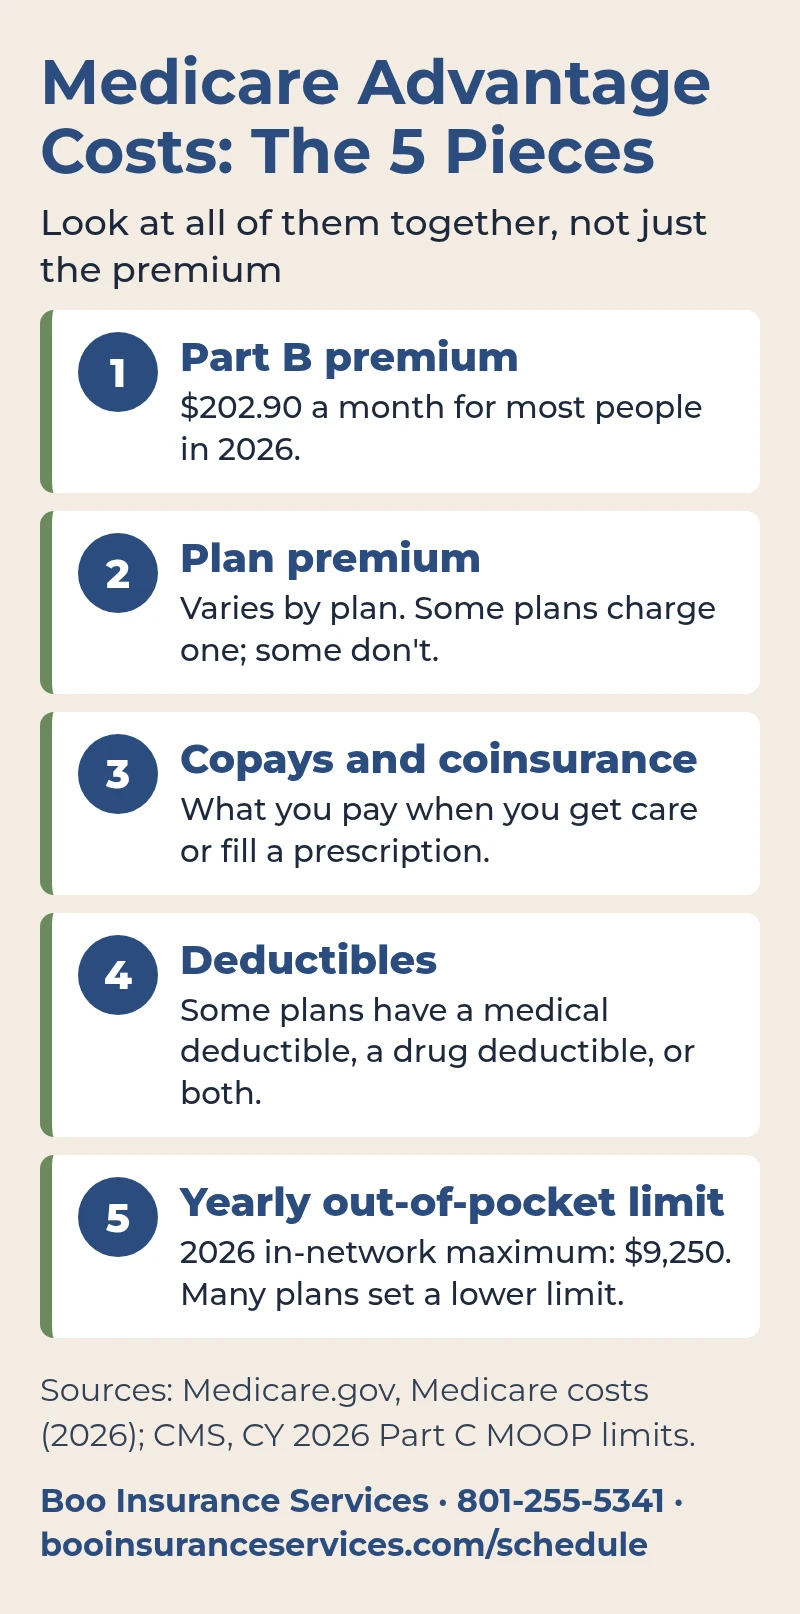
Your costs in a Medicare Advantage plan come from a few places. Look at all of them together, not just the monthly premium.
- Part B premium: $202.90 a month for most people in 2026, or higher if your income is above certain limits. (Medicare.gov – Medicare costs)
- Plan premium: some plans charge a monthly premium on top of Part B; some don’t.
- Copays and coinsurance: what you pay when you see a doctor, fill a prescription or stay in a hospital.
- Deductibles: some plans have a medical deductible, a drug deductible, or both.
- Out-of-pocket limit: every plan has a yearly limit on what you pay for covered Part A and Part B services. For 2026, Medicare’s in-network limit is $9,250, and many plans set a lower one. Once you pay your plan’s limit, the plan pays 100% of your covered services for the rest of the calendar year. PPO plans also have a combined in- and out-of-network limit ($13,900 maximum in 2026). (CMS – Medicare Advantage rates & statistics (CY 2026 MOOP limits) · Medicare.gov – Medicare costs)
Original Medicare alone has no yearly out-of-pocket limit. That cap is one of the biggest structural differences between the two.
NETWORKS & RULES
Networks, referrals and prior authorization
HMO and PPO networks
Most Medicare Advantage plans in Utah are HMOs or PPOs.
- HMO: you generally use the plan’s network doctors and hospitals, except in emergencies. Many HMOs require a referral to see a specialist.
- PPO: you can see out-of-network providers, but you usually pay more. Referrals often aren’t required.
Networks can change during the year. A doctor who is in-network today may not be next year, so check every year during Open Enrollment.
Prior authorization
Many plans require approval (prior authorization) before covering some services. In most cases, Original Medicare doesn’t. (Medicare.gov – Compare Original Medicare and Medicare Advantage) Plans may require it, such as certain scans, procedures or a skilled nursing stay. Ask how a plan handles this for the care you use most.
Travel and living part of the year elsewhere
Plans are built around a service area. Emergency and urgent care are covered anywhere in the U.S., but routine care outside the area may be limited. If you spend winters in Arizona or visit family out of state for months at a time, ask how the plan handles that before you join.
PROS AND CONS
Pros and cons of Medicare Advantage
Where Medicare Advantage can fit well
- A yearly out-of-pocket limit on covered medical services.
- Drug coverage and medical coverage in one plan, with one card.
- Lower monthly premiums than many other coverage paths.
- Extra benefits that Original Medicare doesn’t include.
Where it can fall short
- You’re limited to a network, or pay more outside it.
- Referrals and prior authorization can add steps before care.
- Copays add up in a year with a lot of care.
- Routine care away from home can be limited.
- If you later want a Medicare Supplement, you may have to answer health questions.
Weighing a Medicare Supplement instead? Read Medicare Advantage vs. Medicare Supplement, take the 2-minute Medicare Advantage vs. Medigap quiz, or see how Medicare Supplement plans work in Utah.
ENROLLMENT DATES
When you can join or change Medicare Advantage plans in Utah
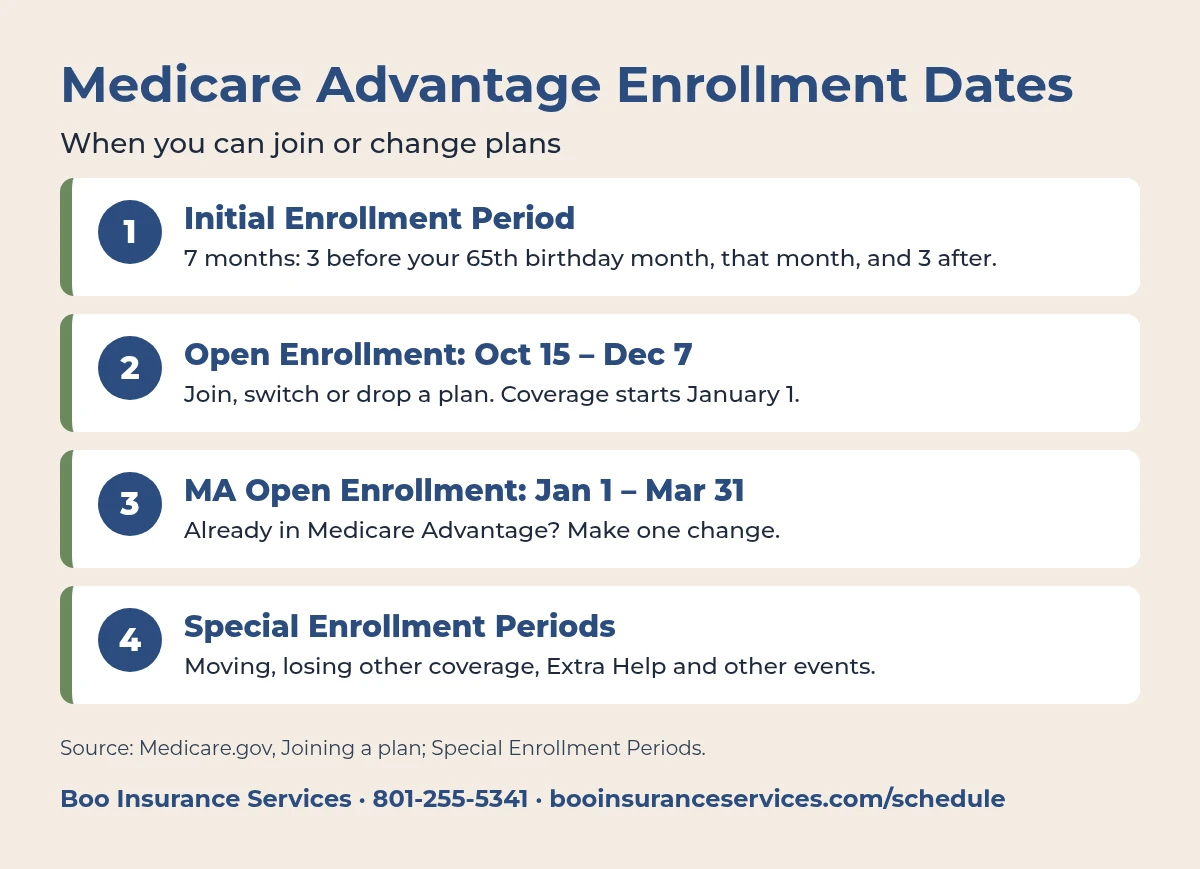
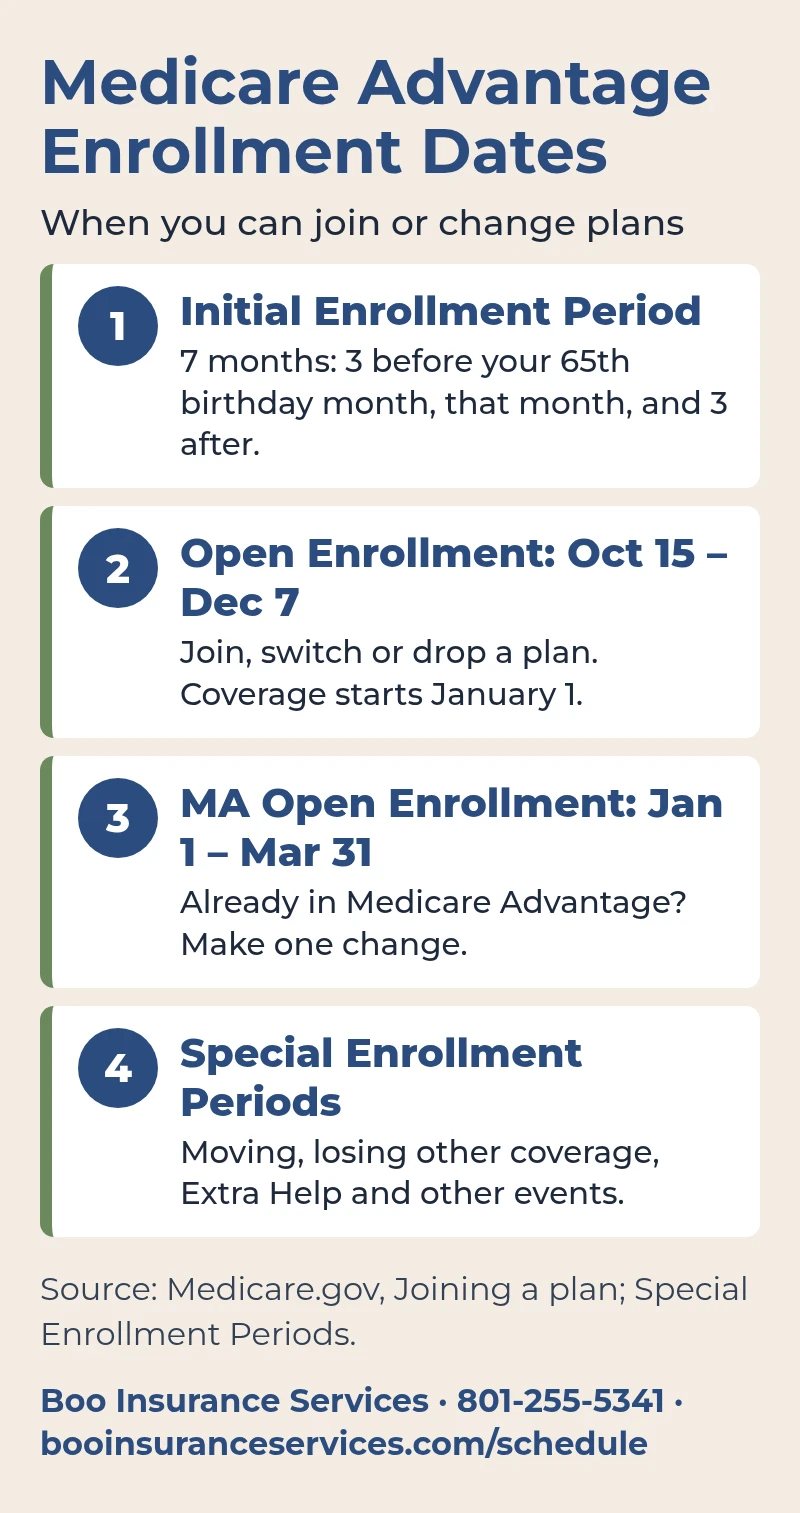
- Initial Enrollment Period: 7 months around your 65th birthday (3 months before, your birthday month and 3 months after). You need Part A and Part B to join.
- Open Enrollment Period: October 15 to December 7 each year. Join, switch or drop a plan for coverage that starts January 1.
- Medicare Advantage Open Enrollment Period: January 1 to March 31, only if you’re already in a Medicare Advantage plan. You can switch to another Medicare Advantage plan or go back to Original Medicare, once.
- New to Medicare Advantage at 65: if you joined a plan during your Initial Enrollment Period, you can switch plans or go back to Original Medicare within your first 3 months of having Medicare.
- Special Enrollment Periods: certain events, such as moving, losing other coverage or qualifying for Extra Help, open a window outside the usual dates.
Sources: Medicare.gov – Joining a plan · Medicare.gov – Special Enrollment Periods
See every Utah date in one place on the Medicare enrollment dates in Utah page, or get ready for this fall with the Utah Medicare Open Enrollment guide. If your current plan won’t be offered next year, read what to do if your Medicare Advantage plan is ending in 2027.
7 CHECKS
Comparing Medicare Advantage plans Utah seniors are offered: 7 checks
The plans available in Salt Lake County aren’t the same as those in Washington County or Cache County. Before you enroll, check these seven things for each plan you’re considering.
- Your doctors and hospitals. Confirm each one is in-network for next year. Call the office too, not just the online directory.
- Your prescriptions. Check that each drug is on the plan’s formulary, its tier, and any prior authorization or step therapy rules.
- Your total yearly cost. Add the plan premium, likely copays and the drug costs. Then look at the out-of-pocket limit for a bad year.
- The service area and travel. Make sure the plan serves your county and fits how much time you spend away.
- Referrals and prior authorization. Know what needs approval before you need it.
- Extra benefits. Read the limits on dental, vision and hearing. A large dental limit doesn’t help if you need hearing aids.
- Star ratings. Medicare rates plans from 1 to 5 stars on quality and service.
You can compare every plan in your ZIP code on Medicare.gov’s plan finder. You can also call 1-800-MEDICARE or Utah’s SHIP program for neutral counseling.
Want help running these 7 checks?
There’s no cost to you for my help.
LOCAL HELP
Why Utahns work with a local Medicare agent
I’m an independent agent, so I can show you options from more than one company. I’ve been licensed since 2014, have helped 1,000+ Utahns with Medicare, and Boo Insurance Services is 5-Star Rated on Google. Reviews are by phone or video, so it works wherever you live in Utah. There’s no cost to you for my help.
COMMON QUESTIONS
Frequently asked questions
They’re Medicare-approved private health plans, also called Part C, that cover your Part A and Part B services. Most include Part D drug coverage. The plans you can join depend on your Utah county, and you keep paying your Part B premium.
Yes. You keep paying your Part B premium, which is $202.90 a month for most people in 2026. Some plans also charge a monthly plan premium, and you pay copays or coinsurance when you get care.
Only if your doctor is in the plan’s network, or if you’re in a PPO and accept higher out-of-network costs. Networks can change each year, so confirm your doctors before you enroll and again each fall.
Yes. Every plan has a yearly out-of-pocket limit for covered Part A and Part B services. For 2026, Medicare’s in-network limit is $9,250, and many plans set a lower one. Original Medicare alone has no yearly limit.
During Open Enrollment, October 15 to December 7, for coverage starting January 1. If you’re already in a Medicare Advantage plan, you can also make one change from January 1 to March 31. Some life events open a Special Enrollment Period.
Emergency and urgent care are covered anywhere in the U.S. Routine care outside your plan’s service area may be limited or cost more. If you spend months away from Utah each year, ask the plan how it handles that before you join.
Yes. You need both Part A and Part B, and you must live in the plan’s service area. You keep paying your Part B premium while you’re in the plan.
Get your Medicare Advantage plans Utah review
Bring your doctor list and your prescriptions. I’ll walk through the plans in your county, explain the trade-offs in plain words, and you decide.
Ready to compare?
There’s no cost to you for my help.
NEXT STEP
Sources
- Medicare.gov, Compare Original Medicare and Medicare Advantage: https://www.medicare.gov/basics/get-started-with-medicare/get-more-coverage/your-coverage-options/compare-original-medicare-medicare-advantage
- Medicare.gov, Medicare costs (2026 Part B premium and deductible): https://www.medicare.gov/basics/costs/medicare-costs
- Medicare.gov, How much does Medicare drug coverage cost?: https://www.medicare.gov/health-drug-plans/part-d/basics/costs
- Medicare.gov, Joining a plan: https://www.medicare.gov/basics/get-started-with-medicare/get-more-coverage/joining-a-plan
- Medicare.gov, Special Enrollment Periods: https://www.medicare.gov/basics/get-started-with-medicare/get-more-coverage/joining-a-plan/special-enrollment-periods
- Medicare.gov, Plan finder: https://www.medicare.gov/plan-compare/
- CMS, Medicare Advantage rates & statistics (CY 2026 MOOP and cost-sharing limits): https://www.cms.gov/medicare/payment/medicare-advantage-rates-statistics
- CMS, Medicare Monthly Enrollment: https://data.cms.gov/summary-statistics-on-beneficiary-enrollment/medicare-and-medicaid-reports/medicare-monthly-enrollment
- Utah DHHS Aging & Adult Services, SHIP: https://daas.utah.gov/seniors/
Last updated: October 2026
Disclaimer: We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Not connected with or endorsed by the United States government or the federal Medicare program. National Producer Number: 17255694
About the author: Fores Boo is a licensed independent Medicare agent, NPN 17255694, with Boo Insurance Services, 61 W 13490 S Ste 201, Draper, UT 84020 · 801-255-5341. Reviews are by phone or video.